

Bright: Loans & Credit Builder
by Bright Money
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
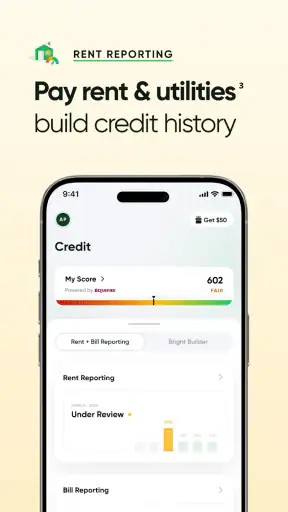
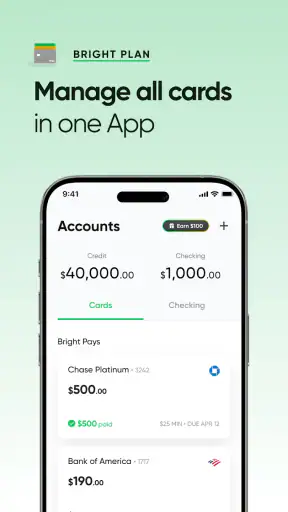
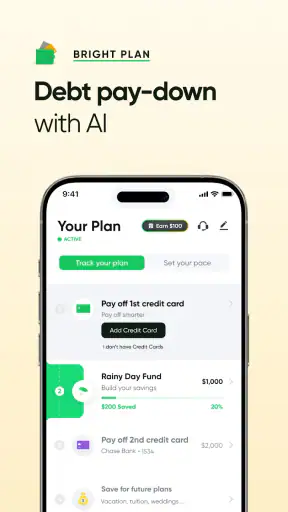
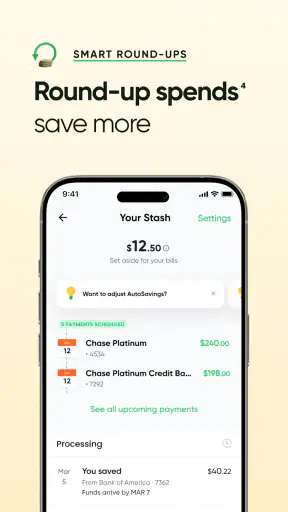
 Analysis by Getfullapps
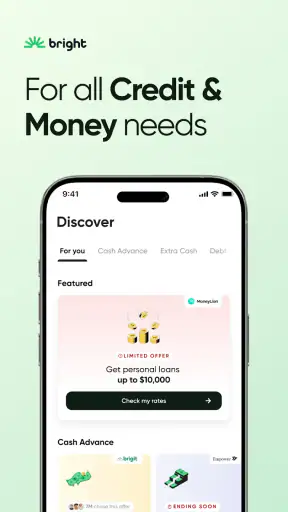
I approached Bright as a practical finance app rather than a quick-fix credit product. Developed by Bright Money, it is aimed at people who want help building credit, understanding borrowing options, and potentially finding loans or credit cards in one place. The first impression is appealing because the purpose is easy to understand: instead of juggling several financial websites, you get a guided starting point on your phone.
That convenience matters most when your credit history is limited, uneven, or simply difficult to interpret. I found the app more useful as a planning companion than as a promise of instant approval or effortless financial improvement. Its value depends on how consistently you review what it shows, how carefully you read each offer, and whether you are willing to make the underlying money habits yourself.
Bright is free to install and available to an Everyone-rated audience, with support for Android 8.0 and later. Its current version is 1.61.1. The app has reached over a million installs and holds a 4.6 average from roughly 159 thousand ratings, which suggests that many users find the general concept approachable. Still, popularity should not replace careful checking when borrowing is involved.
From an appealing first week to a more demanding routine
I found that the shift from exploring Bright to using it as part of a routine is where a clear purpose matters most. A brief check-in can help me stay deliberate, while opening it without a question in mind risks turning financial guidance into more choices to manage. The next section looks at how the app’s presentation and navigation affect that ongoing effort.
Why the first week feels useful
During the first week, the strongest part of Bright is the sense of direction. Credit can feel unnecessarily mysterious: a score changes, a lender uses different criteria, and a card or loan offer may look attractive until the repayment details are examined. Bright puts the credit-building idea at the center, so the app feels more focused than a general budgeting tool.
I especially liked the way this kind of app can turn a vague goal into a sequence of decisions. A user may begin by asking, “How can I improve my credit?” and then move toward questions about borrowing, repayment, and eligibility. That progression is more helpful than simply displaying a score without explaining what the next practical step might be.
The artificial-intelligence angle also makes the initial experience feel more personal than a static article or calculator. Instead of searching through broad financial advice, you can use the app as a starting point for questions connected to your situation. I would still treat its guidance as an aid to judgment, not as a substitute for reading lender terms or checking information independently.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic first-week use case would be someone preparing to rent a new apartment. They may have income but a thin credit file and no clear idea whether applying for another card is sensible. Bright can help organize the questions they should ask before applying: whether the product fits their current position, what repayment would require, and whether improving existing habits should come before taking on new credit.
The difference between guidance and approval
This distinction is important. Bright presents itself around loans, credit cards, and credit building, but an app cannot remove the lender’s decision process. Approval, terms, eligibility, and suitability remain separate matters. I would never open the app expecting a guaranteed loan or assuming that a recommendation means an offer is automatically affordable.
That may sound obvious, yet it is the main point a new user should keep in mind. Financial apps can make a borrowing decision feel smooth because the screens are easier than a traditional application. The debt itself is not smoother. Before accepting anything, I would compare the full repayment obligation, check fees and timing, and consider how the payment would fit beside rent, utilities, food, and existing balances.
Bright is therefore strongest in the early stage of decision-making. It can help you frame the problem and identify possible routes. It is less suitable for anyone who wants a single definitive answer or who is already struggling to make current payments. In that situation, adding another application may create more pressure rather than solve the original issue.
What makes the app different from usual alternatives
The usual alternatives are a bank application, a credit-monitoring service, a spreadsheet, or a general personal-finance app. A bank may provide a direct product but usually has no reason to help you compare the broader decision. A spreadsheet gives control but requires you to know what to track. A monitoring service may show credit information without offering a clear route from information to action.
Bright occupies the space between those options. Its appeal is the guided connection between credit education, possible borrowing, and credit-card discovery. That is useful for a person who feels overwhelmed by separate tools. The trade-off is that a guided experience can encourage passive trust. I would use Bright to form a shortlist of questions and options, then verify the important details at the lender or card provider before proceeding.
One practical tip is to avoid treating every suggestion as a task that must be completed immediately. During the first week, I would make a simple note of the actions that are genuinely relevant, such as reviewing current balances or understanding an unfamiliar credit term. I would not apply for several products merely because the app makes them easy to explore. Protecting your decision quality is more valuable than filling the app with activity.
Where the month-to-month value comes from
Bright earns a longer place on the phone only if it helps turn credit improvement into a repeatable habit. The app is not the habit by itself. The habit is checking obligations, paying attention to timing, avoiding unnecessary borrowing, and noticing whether a financial choice supports the goal you set at the beginning.
For me, the most durable use would be a short monthly review. I would open the app after checking my own account statements and ask whether my financial situation has changed, whether a suggested product still makes sense, and whether I am moving toward a stable credit profile rather than simply chasing a higher number. This keeps the app in a supporting role and prevents it from becoming the only place where I look at money.
A useful workflow is to separate discovery from action. First, use Bright to understand a possible loan or card route. Next, write down the total cost, payment schedule, and reason for considering it. Finally, wait long enough to decide without the pressure of an attractive interface. This small pause is a non-obvious advantage of using the app deliberately: it turns a fast recommendation into a slower, more responsible decision.
The app can also be useful when a life change affects your plans. Moving, changing jobs, preparing for a major purchase, or trying to rebuild after missed payments can make old assumptions unreliable. A monthly review gives you a chance to reassess rather than continuing with a plan that was designed for a different situation.
Who gets the most lasting value
I think Bright is best suited to a newcomer who wants credit concepts explained in a more approachable way, or to someone who needs a central place to think about loans and cards before taking action. It may also suit a user who tends to avoid financial tasks because the terminology feels intimidating. The guided format lowers the barrier to starting.
It is less compelling for someone who already has a detailed system, understands credit products well, and regularly compares offers directly. That person may find a dedicated bank tool, a credit report service, or a personal spreadsheet more precise. Bright’s convenience is most valuable when organization and confidence are the problem, not when the user already has those covered.
I would also be cautious if your main goal is debt relief rather than credit building. A credit-focused app can help you think about future eligibility, but it does not automatically make existing debt manageable. If your budget is already strained, the better choice may be a nonprofit adviser, a direct conversation with creditors, or a simple repayment plan that does not involve applying for more credit.
The maintenance burden after the novelty fades
The first-week excitement comes from discovery. The maintenance phase is quieter and more demanding because it requires judgment. You need to keep your personal information and financial context current, revisit decisions when circumstances change, and resist the temptation to interpret every recommendation as progress.
That maintenance is not necessarily heavy, but it is easy to neglect. A finance app can be opened often without producing better financial behavior. I would rather use Bright briefly and intentionally than check it repeatedly without acting on anything. A calendar reminder for a monthly review can be more valuable than turning the app into a daily habit.
There is also a mental cost to seeing borrowing options when your original goal was simply to improve credit. Loan and card discovery can be useful, but it may widen the number of decisions you feel you should make. I found that the app works better when I define the goal before opening it: learn, compare, or review. Without that boundary, the experience can drift from education into unnecessary shopping.
Another maintenance issue is verification. Financial recommendations deserve more scrutiny than ordinary app suggestions. I would check the lender’s own terms, confirm repayment amounts, and look for charges or conditions before moving forward. Bright can shorten the search, but it should not shorten the reading. The most important details are often the ones a user is tempted to skip because the overall offer looks convenient.
What can cause fatigue over time
The largest source of fatigue is repetition without visible progress. Credit improvement is not usually dramatic from one visit to the next, so a user may eventually wonder why they should keep opening the app. If Bright becomes a place where you repeatedly look at similar guidance without changing your financial routine, its value will decline.
A second source is recommendation overload. Even when options are relevant, more choices do not always make the decision easier. Someone who wants one clear next step may become tired of comparing possibilities, especially if each one requires separate research. My solution would be to limit each review session to one question and one possible action.
There is also the risk of confusing a polished explanation with personal suitability. A product can sound reasonable and still be wrong for your income pattern, emergency savings, or existing commitments. I would skip any application step if I could not explain how the payment would be handled in a difficult month. That rule is more reliable than enthusiasm generated by a helpful interface.
Privacy and trust are naturally part of the decision whenever a finance app is involved. I would read the app’s current permission and privacy information before connecting accounts or entering sensitive details, and I would use a strong device lock. Those precautions are not a criticism unique to Bright; they are a sensible standard for any tool that deals with personal financial information.
Small techniques that improve the experience
My first technique is to create a written “reason for use” before exploring products. For example, the reason might be understanding credit-building options before a rental application, not finding the fastest available loan. This keeps the app aligned with a real need and makes it easier to ignore options that do not serve that need.
My second technique is to compare the cost of inaction with the cost of borrowing. If the goal is to build credit, taking a loan is not automatically better than managing existing accounts carefully. Bright is more useful when it helps you examine that trade-off rather than pushing you toward a product simply because it is available.
My third technique is to keep a short record outside the app of what I decided and why. A note with the date, the goal, and the next review point prevents repeated reconsideration. It also exposes whether the app is helping you make decisions or merely giving you new information. That distinction is crucial for long-term value.
Finally, I would review the app after a few cycles and ask whether it has reduced confusion, improved consistency, or helped me avoid a poor choice. If the answer is no, uninstalling it is reasonable. A free app still has an attention cost, and a finance tool should earn that attention through useful decisions rather than constant presence.
My long-term verdict
Bright has a clear place for users who want a friendlier entry point into credit building, loans, and credit cards. The developer, Bright Money, has made an app that feels more focused than a basic budgeting tracker and more action-oriented than a page of general financial advice. Its strong average rating and broad install base show that the format resonates with many people.
My recommendation is conditional but positive: use it as a guide, not as an authority; as a monthly checkpoint, not a daily obligation; and as a way to prepare better questions, not as a guarantee of approval or improved finances. The app’s lasting value comes from the habits it supports outside the screen.
For a beginner, that can be enough reason to keep it installed. For an experienced borrower with a reliable system, the extra layer may not justify the attention. I would also skip it if I were looking for emergency cash without a clear repayment plan, because convenience can hide how serious that commitment is.
In the end, Bright survives the novelty test when the user gives it a narrow, practical job: understand the next credit decision, review progress, and avoid impulsive borrowing. Used that way, it can remain a helpful finance companion. Used as a shortcut around careful comparison and personal budgeting, it is unlikely to deliver lasting value.
Pros
- User-friendly interface for easy navigation.
- Quick loan approval process.
- No hidden fees or charges.
- Helps improve credit score with timely payments.,24/7 customer support available.
Cons
- Requires access to personal financial data.
- High APR for some loan options.
- Limited loan amounts for new users.
- Not available in all regions.
- App crashes occasionally on some devices.
FAQs for Bright: Loans & Credit Builder
What is Bright: Loans & Credit Builder?
Bright: Loans & Credit Builder is a financial app designed to help users manage their credit score and access personal loans. It offers tools for building credit, tracking spending, and improving financial health. The app aims to simplify financial management and provide users with the resources they need to achieve their credit goals.
How does Bright help improve my credit score?
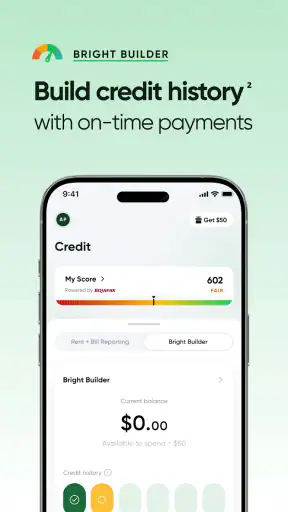
Bright assists in improving your credit score by offering personalized tips and strategies based on your financial habits. It monitors your credit activity and provides insights on how to maintain a positive score. The app also helps automate payments to ensure bills are paid on time, a crucial factor in credit scoring.
Is Bright secure and how does it protect my data?
Bright uses advanced encryption and security protocols to protect your personal and financial information. The app is committed to maintaining user privacy and complies with industry standards to ensure data is securely stored and transmitted. Users can trust that their information is safeguarded against unauthorized access.
What types of loans can I access through Bright?
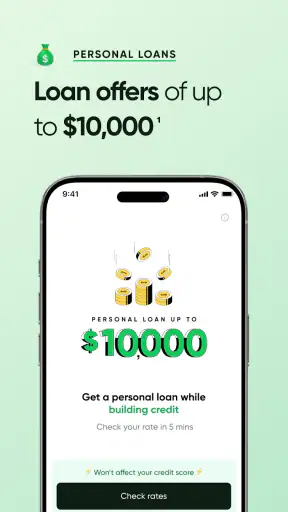
Bright offers access to personal loans tailored to your financial profile and credit needs. The app provides various loan options with competitive interest rates and flexible terms. Users can apply directly through the app, and Bright guides them through the process to find the best loan to suit their circumstances.
Are there any fees associated with using Bright?
While Bright offers many of its features for free, there may be fees associated with certain premium services or loan products. It's important for users to review the terms and conditions within the app to understand any potential costs. Bright aims to be transparent about all fees, providing clear information before any charges are incurred.

Bright: Loans & Credit Builder
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@brightmoney.co, visit https://www.brightmoney.co, or review their https://www.brightmoney.co/legal/privacy-policy/.










